Reddit Fell 36% on a Warning About Users Who Bring In 4% of Its Revenue
October 31, 2026 · Reddit, Inc. (RDDT)
profitmonk
Summary
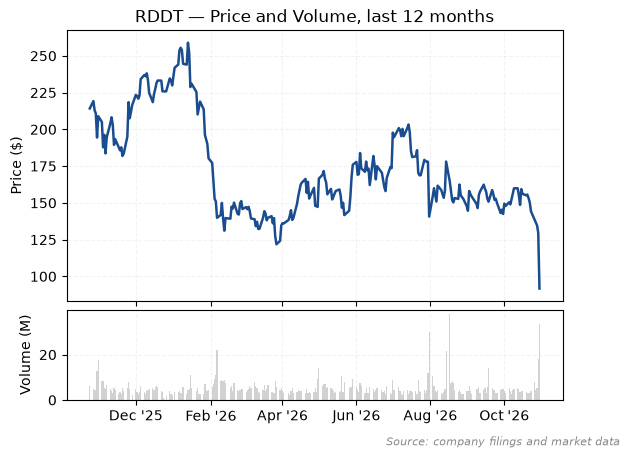
- Reddit grew revenue 53% in the third quarter, and the stock still fell 36.4% in five trading days after a soft fourth-quarter guide and a warning that daily users could fall by a low double-digit percentage.
- The users Reddit expects to lose are worth little. A logged-out visitor earns about one-sixth of a logged-in one, so the warned fall costs at most 3% to 4% of guided fourth-quarter revenue.
- I do not expect Reddit to beat 2028 consensus. My base case is $4.64B of revenue, 14% below the $5.40B consensus, and it assumes every dollar from logged-out visitors is gone by then.
- The edge is the price. At $91.67 the business is valued at 7.2 times my bear-case 2028 EBITDA, provided the 49% adjusted EBITDA margin Reddit guided for the fourth quarter holds.
- The test is the fourth-quarter report, listed for 4 February 2027: logged-in daily users need to hold at 53.5 million or better.
The Quarter That Broke the Stock
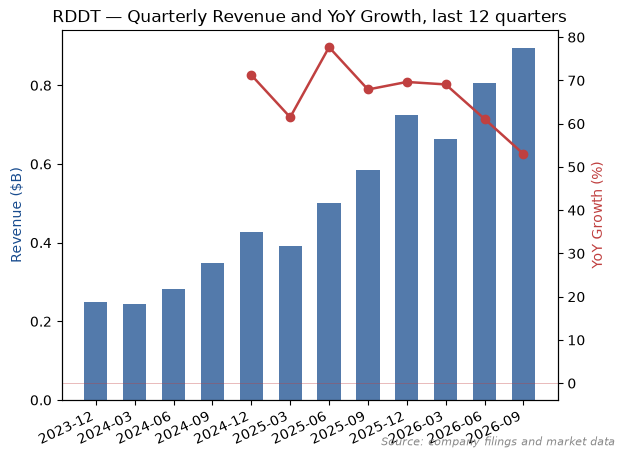
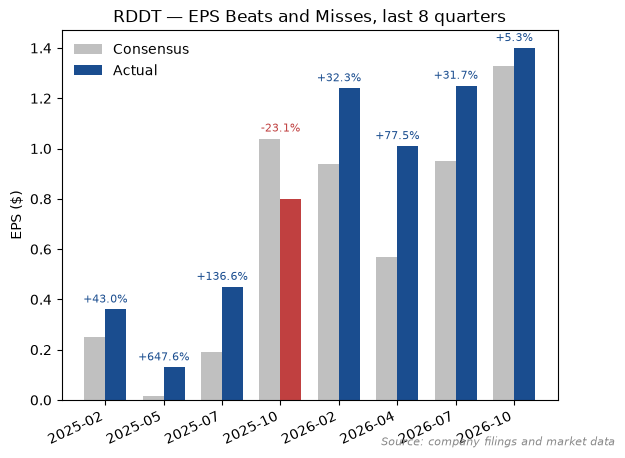
Reddit reported its third quarter after the close on 29 October, and the numbers themselves were excellent. Revenue rose 53% to $895M and free cash flow nearly doubled. Then chief executive Steve Huffman told analysts what was happening to his traffic.
"During October, we have seen that search traffic has dropped by more than 1 million referrals on average per week," he said. "If this rate of decline continues, current trends would suggest that total DAUqs could fall in Q4 by a low double-digit percentage from our current base of 130 million DAUqs." DAUq is Reddit's count of daily active uniques, the distinct people who visit in a day.
The guidance made it worse. Reddit guided fourth-quarter revenue to $1.00–1.03B, and the midpoint sits 3% below Bloomberg's consensus. MarketWatch reported that 30 October was the stock's worst session since it listed, and over five trading days it fell 36.4% to $91.67.
The brokers followed. Benzinga and TipRanks headlines that day showed KeyBanc downgrading to Sector Weight on "weaker-than-expected search traffic trends" and Oppenheimer going to Sell, while Needham and Truist kept Buy ratings.
My argument is that the market sold the wrong number. The users Reddit is losing are the ones it barely earns from, and the price now assumes the worst case for the ones that matter.
A 21-Year-Old Forum That Went Public in 2024
Reddit is a San Francisco company that runs more than 100,000 active communities, called subreddits, where people post and argue under pseudonyms about everything from skiing to insurance. It was founded in 2005 and listed on the New York Stock Exchange in March 2024, and Huffman, a co-founder, runs it.
What it owns is an archive. Users have written about 27 billion posts and comments, adding 1 billion in the third quarter alone, and the site drew 130.3 million daily uniques in the quarter.
About 94% of revenue comes from advertising sold by auction against those conversations. The rest comes from licensing the archive to AI companies, and the annual report says two partners hold substantially all of that contract value. Analysts on the call named them as OpenAI and Google, and Huffman did not dispute it.
Reddit joined the S&P 500 on 18 August. It is now worth about $17.64B, of which $3.03B is cash and marketable securities, and the filings I read show no funded debt.
Two Lines of Revenue, and the US Earns Most of It
Advertising is the business, and the US is where it earns. Reddit does not report gross profit by line, so the company-wide gross margin of 91.5% stands for all of them.
| Line | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Advertising | $847M | +54% | |
| Other (data licensing) | $48M | +35% | |
| US | $719M | $480M | +50% |
| International | $176M | $105M | +67% |
| Total revenue | $895.0M | $584.9M | +53% |
Advertising is now growing on price. Chief operating officer Jen Wong said pricing outpaced impressions this quarter, while clicks rose more than 50% and conversions more than tripled. That reverses 2025, when the annual report credited growth mainly to more impressions and only "to a lesser extent" to price.
Licensing is small, about 5% of revenue ($48M of $895M). Margin by line is not disclosed. The annual report says the revenue is recognised "generally ratably over the license period," and the growth reflects deals signed in 2024 and 2025.
The US carries the money, earning 80% of revenue from a user base smaller than the international one. International revenue grew faster, at 67%, helped by machine translation, which Reddit runs in 35 languages.
How an Ad Marketplace Is Measured
Of the numbers investors trade Reddit on, the headline user count is the least useful. The one that matters is logged-in daily uniques: people with an account who are signed in, which gives Reddit far better signals for targeting ads.
| Daily uniques, Q3 2026 | Users | Year on year |
|---|---|---|
| Logged-in | 53.5M | +7% |
| of which US | 23.4M | +1% |
| of which international | 30.1M | +11% |
| Logged-out | 76.8M | +17% |
| of which US | 27.3M | −4% |
The paying base is still growing, but the growth is international. US logged-in users rose just 1%, and US logged-out users fell 9.3% in a single quarter, which is where Google's retreat shows up first.
The second number is ARPU, or average revenue per user, which Reddit calculates on daily uniques. Globally Reddit earns about 39% of what Meta does per user, but its ARPU is growing at 36% a year against Meta's 22.5%. Those two rates anchor my model. ARPU needs care this quarter, though, because when low-value logged-out users leave it rises mechanically even if nothing improves. So I build the model on revenue per logged-in user.
The third number is margin, and this business is unusually cheap to run. Serving one more ad costs almost nothing, so gross margin has stayed above 90% for nine straight quarters, and chief financial officer Drew Vollero said incremental adjusted EBITDA margin was 54%.
Stock-based compensation is the cost to watch, at about 15% of revenue including related taxes. Buybacks have absorbed it so far, and net of repurchases the share count rose only 0.1% this year.
What Changed: Google Fed Reddit, and Now It Starves It
Two years ago Reddit lost money. It lost $484.3M in 2024, the year it listed, and earned $529.7M in 2025. Google helped feed that growth, and even this quarter logged-out daily uniques, the search-referred group, were still up 17% year on year.
Now Google answers the question on its own page. Huffman blames AI Overviews and AI Mode: "what started as a feature is now the full search experience… the experiences themselves are not traffic drivers." Outside the US he sees a second hit, because "we believe our machine-translated content is also being ranked lower."
Reddit is not alone. Chartbeat's 2026 Publisher Playbook, reported by Search Engine Journal in September, measured a 40.2% fall in Google Search referrals to publishers between July 2025 and July 2026.
The macro adds pressure of its own. The annual report says inflation, interest rates, tariffs and geopolitical risk "have created uncertainty in the advertising market."
The Demand Story: Advertisers Pay for Intent
Reddit tells advertisers that people come to the site to decide what to buy. Wong said "half of U.S. shoppers say they come to Reddit to verify AI recommendations," a company claim whose methodology Reddit has not disclosed.
The quarter's results back the pitch. Shopping and app-install campaigns each grew more than 95%, and mid-market active advertisers rose more than 50%, with business and finance, pharma and travel the strongest verticals.
Wong's example was Ethnotek, a backpack and accessories company, whose Dynamic Product Ads through Reddit's Shopify integration delivered a "4x return on advertising spend and a 40% more efficient CPA." CPA is cost per acquisition, what an advertiser pays for each sale.
The next leg of growth is Reddit Max, the automated campaign product launched in beta in January. Max advertiser adoption "more than tripled quarter-over-quarter," Wong said, and Smartly became the first third party to integrate Max through its API.
On busy days demand already outruns supply. Vollero said that in September there were "some bookings that we weren't able to deliver on a couple of days," and Reddit enters each quarter with about half its business already booked.
The advertiser base is also spreading out. The top ten advertisers made up about 21% of revenue in 2025, down from about 25% in 2024.
Why Losing a Tenth of Users Costs So Little
Huffman said logged-in and app users carry "over 80% of the monetization." That splits third-quarter revenue into at least $716M from logged-in and app users and at most $179M from logged-out web visitors.
Divide by the users and the gap is stark. Each logged-in user earned about $13.38 in the quarter, and each logged-out user at most $2.33, about one-sixth as much.
Huffman's warning implies losing 13 million to 17 million daily uniques, almost all of them logged out. At $2.33 each, they bring in at most 3% to 4% of the fourth-quarter guide, which is why the guide still shows about 40% growth while users fall by double digits.
The Constraint: Google Holds the Front Door
Reddit has no factory to build, since capital spending was $1.2M in the quarter. Its constraint is traffic, and above all traffic from Google.
Google sits on three sides of Reddit at once. It sends the referrals, it pays for the archive (Reuters put that deal at $60M a year when it was signed in 2024), and it competes for ad budgets. Huffman said Reddit is still a top search term on Google and that "Google is crawling us as hard as ever." It simply sends fewer people.
Reddit's answer is to turn visitors into account holders. Huffman said "only about 13% of eligible mobile-web users are seeing the app conversion prompt," which he presents as unused capacity. In the US, paid marketing is shifting from web reach to app installs because, Vollero said, "low retention rates have hurt ROI" on web campaigns. Wong said US app-install users so far retain at rates comparable to organic ones.
The larger move is a login wall. In the fourth quarter Reddit begins testing logged-in-only access in "select markets outside the U.S." Huffman was candid about the cost, saying Reddit will "likely be trading reach for engagement," and about the unknown: "what the conversion rate is over time, we just don't know."
The wall also guards the archive. "The vast majority of the scraping and stealing of Reddit happens in our logged-out user base," Huffman said, so locking the door protects the corpus that Google and OpenAI pay to license.
None of this resolves in a quarter. First-week retention of new app users is up "over 50% year-over-year," Huffman said, but the login test only starts now, so the first read on conversion comes in 2027.
What It Is Worth: Below Consensus, With Logged-Out Revenue at Zero
I built 2028 revenue from the users who pay and gave logged-out users no credit at all, which is the worst case of the login wall and the Google decline combined. The full arithmetic is in the research brief.
The starting point is 2026. Nine months of revenue plus the fourth-quarter guide gives about $3.375B, and 80% of that, about $2.70B, comes from logged-in and app users. Two observed rates then drive each case: how fast logged-in users grow, and how fast revenue per logged-in user grows.
| 2028 case | Logged-in user growth a year | Revenue per user growth a year | 2028 revenue |
|---|---|---|---|
| Bear | 1% (US, Q3) | 22.5% (Meta, Q3) | $4.14B |
| Base | 7% (global, Q3) | 22.5% (Meta, Q3) | $4.64B |
| Bull | 7% (global, Q3) | 36% (Reddit, Q3) | $5.72B |
| Consensus | $5.40B |
My base case is 14% below the $5.40B consensus and close to the lowest estimate of $4.62B. The whole gap comes from one assumption, because I let Reddit's revenue per user grow only as fast as Meta's does today.
Consensus is less demanding than it looks. To reach $5.40B with nothing from logged-out users, revenue per logged-in user would need to grow about 32% a year, slower than Reddit manages now and faster than Meta. If logged-out revenue merely holds flat, my base case rises to $5.31B, which is on consensus.
So I do not expect Reddit to beat 2028 revenue consensus, and the bull argument rests on the price.
Earnings need one adjustment. Reddit pays a tax rate of about 2% because it still carries valuation allowances against its US deferred tax assets, and Vollero said the company is evaluating "whether those full valuation allowances remain appropriate." Consensus 2028 earnings of $8.51 a share appear to assume the low rate lasts. At a normal 21% rate, the same revenue gives about $6.68.
That is why I value Reddit on EBITDA and cash flow, which the tax change does not touch. At the 49% adjusted EBITDA margin Reddit guided for the fourth quarter, my base case gives $2.27B of 2028 EBITDA, below the $2.73B in KeyBanc's July model, published before its downgrade.
What the Market Is Paying: a Bear Case Priced In
On trailing numbers Reddit costs about what Meta does while growing revenue 53%. Meta is the right peer because it runs the ad machine Reddit is trying to copy. EV/EBITDA compares the value of the whole business, net of cash, with its operating earnings before depreciation.
| Trailing multiple | Meta | ||
|---|---|---|---|
| P/E | 17.7x | 20.7x | 77.5x |
| EV/EBITDA | 15.9x | 13.7x | 40.0x |
| Price/sales | 5.7x | 5.6x | 2.3x |
Pinterest, the other social ad seller, is harder to use because thin GAAP profit distorts its earnings multiple. Reddit's own history is too short to help, since its only profitable full year was 2025, when the stock traded at 81 times earnings.
I picked those peers myself. The shares now sit 65.2% below their 52-week high of $263.50.
My valuation call rests on 2028 EBITDA. Net of cash the business is worth about $14.61B, which is 7.2 times my bear-case EBITDA, a case with logged-out revenue at zero and US logged-in users barely growing. BofA, writing after the print, put Reddit at 7 times its own 2028 EBITDA at about $106, according to Invezz.
| At $91.67 | Bear | Base | Bull |
|---|---|---|---|
| 2028 revenue | $4.14B | $4.64B | $5.72B |
| 2028 EBITDA at a 49% margin | $2.03B | $2.27B | $2.80B |
| EV / 2028 EBITDA | 7.2x | 6.4x | 5.2x |
| P/E on 2028 EPS at a 21% tax rate | 17.9x | 16.0x | 12.9x |
The outside numbers sit above mine. On KeyBanc's pre-downgrade $2.73B of 2028 EBITDA the multiple is 5.3 times. BofA's 7 times at about $106 implies roughly $2.69B, on my share count and cash rather than any method BofA stated.
The P/E row is where the tax rate bites. On the $8.51 consensus the stock is 10.8 times 2028 earnings, but that figure carries the 2% rate. On a like-for-like 21% rate my base case is 16.0 times, so I would not lean on the lower number.
Cash flow points the same way. Third-quarter free cash flow, annualised, is an 8.2% yield on the market value, and still 5.2% after subtracting stock-based compensation.
On my numbers the stock is cheap, because the price treats the bear case as the base case, and the bear case still delivers about $4.1B of 2028 revenue. Reddit bought shares at an average of $149.81 in the third quarter and has $660M left on its buyback authorisation.
The analysts have marked down too, though not to this price. Even the lowest targets in Benzinga and TipRanks headlines on 30 October, $120 from Bernstein and Evercore ISI, sit well above $91.67.
Why Reddit Keeps Its Corner Against Google, Meta and Pinterest
Reddit's moat is the archive and the commercial intent inside it. Google and OpenAI both pay to license the corpus, and Vollero pointed to "so many of the subreddits themselves organized into things like skiing and travel, which monetize themselves." "A lot of our consumers aren't on other platforms," he added.
Google is the competitor that can hurt it most. AI Mode keeps the searcher on Google's page, and Huffman has turned that into a strategy: "Google is teaching people that if you want to come to Reddit, you need to come to Reddit." Google also sells Performance Max to the same advertisers. Its weakness in Reddit's corner is that it needs the content, which is why it keeps crawling and paying to license it.
Meta is both the model and a rival. Its Advantage+ competes with Reddit Max, and its 3.64 billion daily active people give it far more targeting signal. The logged-in push is Reddit's attempt to close that gap. "Pretty much all the major ad platforms have gone through this transition," Huffman said.
Pinterest competes on shopping ads against Reddit's Dynamic Product Ads, which now support catalogs of 20 million products. Its US and Canada ARPU of $8.30 sits below Reddit's US figure of $13.82, though Pinterest divides by monthly users and Reddit by daily ones.
ChatGPT and Perplexity compete for the "ask a person" question. OpenAI is also a licensing partner, and Reddit is suing SerpApi and others, Perplexity among them, in New York over scraping. Wong said Reddit is "pretty skeptical of GEO," the practice of optimising content to appear in AI answers, and does not sell it as an ad product.
What Could Go Wrong: Reddit Listed This Risk Fourth
The annual report saw this coming. Its fourth risk factor reads: "Changes in internet search engine algorithms and dynamics could have a negative impact on traffic for our website and, ultimately, our business." The text adds, "We rely, in part, on internet search engines, such as Google, to generate traffic." That risk sits ahead of profitability in the list, and it came true this quarter.
The first risk factor warns that if Reddit fails "to grow or retain our user base or maintain user engagement, our business… would be harmed." The fifth says "we may not sustain our growth rate," and growth is guided down from 53% to about 40%.
There is also litigation. A securities class action filed in June 2025 alleges Reddit misled investors about Google and AI Overviews. A judge dismissed it with leave to amend in August, and the motion to dismiss the new complaint is due on 23 November.
Three risks the filing does not stress bear on my thesis. The first is that search also feeds future logged-in users, since Huffman said "some of the impact flows through to logged in and app traffic." If logged-in growth falls to the US rate of 1%, my bear case of $4.14B is 23% below consensus.
The second is a shrinking beat. By TIKR's tally, third-quarter revenue topped the high end of guidance by $25M, against $58M to $80M in each of the three prior quarters. JPMorgan's Doug Anmuth asked on the call why the upside was "a little bit less than what we've seen."
The third is licensing. Reddit's remaining performance obligations, the contracted revenue not yet booked, total only $62.4M and run out in 2027. Asked about the licensing talks, Huffman said they could "potentially include not doing a deal." Licensing is about 5% of revenue; its margin is not disclosed.
The assumption most likely to be wrong is my 7% growth in logged-in users. It rests on international markets, where Huffman says Google is ranking translated content lower. If it slips, my base case drifts toward the bear case, which the price already pays for.
What I Am Watching
The test is the fourth-quarter report, listed for 4 February 2027, though Reddit has not confirmed the date. If logged-in daily uniques fall below 53.5 million, the paying base is shrinking and my bull case is wrong. I will also read the first-quarter revenue guide against 2027 consensus, and look for the first conversion data from the non-US login test.
Takeaway
The market sold Reddit on the number Huffman warned about, total daily users, while the users who pay the bills grew 7%. My model gives no credit for logged-out revenue and still lands at $4.64B for 2028, near the low end of consensus. At 6.4 times that case's EBITDA, and 7.2 times the bear case's, the price already reflects my bear case. If logged-in users hold through February, I expect the market to stop pricing the bear case as the base case.
Sources
- Reddit Q3 2026 earnings release (Form 8-K), 29 October 2026
- Reddit Q3 2026 earnings call, 29 October 2026 (Steve Huffman, Jen Wong, Drew Vollero; analysts Doug Anmuth of JPMorgan and Jason Helfstein of Oppenheimer)
- Reddit Form 10-Q for the quarter ended 30 September 2026, filed 30 October 2026
- Reddit Q2 2026 earnings release (Form 8-K), 30 July 2026
- Reddit Form 10-K for fiscal 2025, Items 1, 1A and 7, filed 6 February 2026
- S&P Dow Jones Indices index change announcement, 13 August 2026
- Meta Q3 2026 earnings presentation, 21 October 2026
- Pinterest Q2 2026 earnings release
- Bloomberg consensus for Q4 2026 revenue, as reported by Invezz and TipRanks, 30 October 2026
- Benzinga, TipRanks, Investing.com and Yahoo Finance on analyst rating and target changes, 30 October 2026
- BofA note on 2028 EBITDA, as reported by Invezz, 30 October 2026
- KeyBanc 2028 estimates, July 2026
- TIKR on Reddit's results against guidance, 2026
- MarketWatch on the 30 October 2026 session; New York Post on the Nasdaq selloff, 30 October 2026
- Chartbeat 2026 Publisher Playbook, via Search Engine Journal, 24 September 2026
- Reuters on the Google licensing deal, 2024
- Company filings, reported results, analyst consensus and market price data
- Full working, including the three-case model, the anchor and the valuation bridge:
research/2026-10-31_RDDT.md
Research, not a recommendation. Figures are sourced as cited and were current at publication; nothing here is personalized investment advice.